In the bustling world of small business, mastering bookkeeping can be the key to unlocking your success. It’s more than just organising receipts; effective bookkeeping lays the groundwork for informed decision-making and financial stability. Yet, many entrepreneurs feel overwhelmed by numbers and spreadsheets, missing the opportunity to harness this powerful tool.
This guide outlines ten essential tips that will not only simplify your bookkeeping process but also empower you to take control of your financial health. From setting up an efficient system to understanding your cash flow, these strategies will help you streamline your operations and keep your business on the path to growth. Whether you’re just starting out or looking to refine your current practices, these insights will elevate your bookkeeping game. Get ready to transform your financial management and pave the way toward small business success!
Understanding the Importance of Bookkeeping for Small Businesses
Bookkeeping is the backbone of any successful small business. It involves systematically recording and organising all financial transactions, ensuring that every dollar spent or earned is accounted for. This process allows business owners to track their financial performance, identify trends, and make informed decisions. Without proper bookkeeping, a business can quickly fall into disarray, leading to cash flow problems, missed opportunities, and potentially, failure.
One of the primary benefits of bookkeeping is that it provides a clear picture of a business’s financial health. By keeping accurate records, entrepreneurs can monitor their revenue, expenses, and profits. This information is crucial for budgeting, forecasting, and planning for future growth. It also helps in identifying areas where costs can be cut or where additional investment may be needed. In short, bookkeeping is not just a mundane task, but a strategic tool that can drive business success.
Moreover, good bookkeeping practices ensure compliance with legal requirements and tax obligations. Businesses are required to maintain accurate financial records for tax purposes, and failure to do so can result in penalties and fines. By keeping meticulous records, business owners can provide the necessary documentation during tax season, avoid legal issues, and maintain their reputation with clients, suppliers, and financial institutions. Proper bookkeeping also facilitates smooth audits, providing a clear trail of all financial transactions.
Common Bookkeeping Mistakes to Avoid
Despite its importance, many small business owners make common bookkeeping mistakes that can have significant consequences. One of the most frequent errors is procrastination. Delaying the recording of financial transactions can lead to forgotten entries, inaccuracies, and a backlog of work that becomes overwhelming. It’s essential to establish a routine and stay on top of bookkeeping tasks regularly to ensure accuracy and reduce stress.
Another common mistake is mixing personal and business finances. This can create confusion and make it difficult to track business expenses accurately. It’s crucial to maintain separate bank accounts and credit cards for business transactions. This separation simplifies bookkeeping, ensures that all business-related expenses are captured, and provides a clear record for tax purposes. It also protects personal assets in case of legal issues or business liabilities.
Failing to reconcile accounts regularly is another pitfall. Reconciliation involves comparing your financial records with bank statements to ensure that they match. This process helps identify discrepancies, such as missing transactions or errors, and provides an opportunity to correct them promptly. Without regular reconciliation, mistakes can accumulate, leading to significant financial discrepancies and potential issues with cash flow management.
Essential Bookkeeping Tools and Software
In today’s digital age, leveraging technology can greatly simplify bookkeeping tasks and improve accuracy. There are numerous bookkeeping tools and software available that cater to the needs of small businesses. These tools offer features such as automated transaction recording, expense tracking, invoicing, and financial reporting. By using these tools, business owners can save time, reduce manual errors, and gain real-time insights into their financial status.
One popular bookkeeping software is Xero, which offers a range of features suitable for small businesses. Xero allows users to manage income and expenses, track sales and sales tax, create invoices, and generate financial reports. It also integrates with bank accounts and credit cards, enabling automatic transaction imports and reducing data entry.
When choosing bookkeeping software, it’s important to consider factors such as ease of use, scalability, and integration with other business tools. Many software options offer free trials, allowing business owners to test their features and determine the best fit for their needs. Additionally, investing time in training and familiarising oneself with the chosen software can maximise its benefits and ensure that bookkeeping tasks are performed efficiently.
Setting Up Your Bookkeeping System
Setting up an effective bookkeeping system is a critical step in managing your business finances. The first step is choosing the right bookkeeping method: cash basis or accrual basis. The cash basis method records transactions when cash is received or paid, making it simpler and suitable for small businesses with straightforward transactions. The accrual basis method, on the other hand, records transactions when they are incurred, providing a more accurate picture of financial health, especially for businesses with complex transactions or inventory.
Once the method is chosen, the next step is selecting the right chart of accounts. This is a list of all the financial accounts in the company’s general ledger, categorised into assets, liabilities, equity, income, and expenses. A well-organised chart of accounts lays the foundation for accurate record-keeping and financial reporting. It’s essential to customise the chart of accounts to fit the specific needs of your business, ensuring that all relevant financial activities are captured.
Implementing a system for recording transactions is the final step in setting up your bookkeeping system. This involves deciding how transactions will be recorded, whether manually or using software, and creating a consistent process for entering and categorising data. It’s important to establish a routine for recording transactions, such as daily or weekly, to ensure that records are kept up-to-date. This routine helps prevent errors, ensures accuracy, and provides timely financial information for decision-making.
The Role of Bookkeeping in Tax Preparation
Bookkeeping plays a vital role in tax preparation, ensuring that all financial transactions are accurately recorded and categorised. Proper bookkeeping provides the necessary documentation to support income and expense claims, reducing the risk of errors and audits. By maintaining organised and up-to-date records, business owners can confidently prepare their tax returns, knowing that all required information is readily available.
Accurate bookkeeping helps identify deductible expenses, which can significantly reduce tax liability. Common deductible expenses include office supplies, travel, advertising, and employee wages.
By keeping detailed records of these expenses, business owners can maximise their deductions and minimise their tax burden. Additionally, bookkeeping software often includes features that categorise expenses and generate reports, making it easier to identify and track deductible expenses throughout the year.
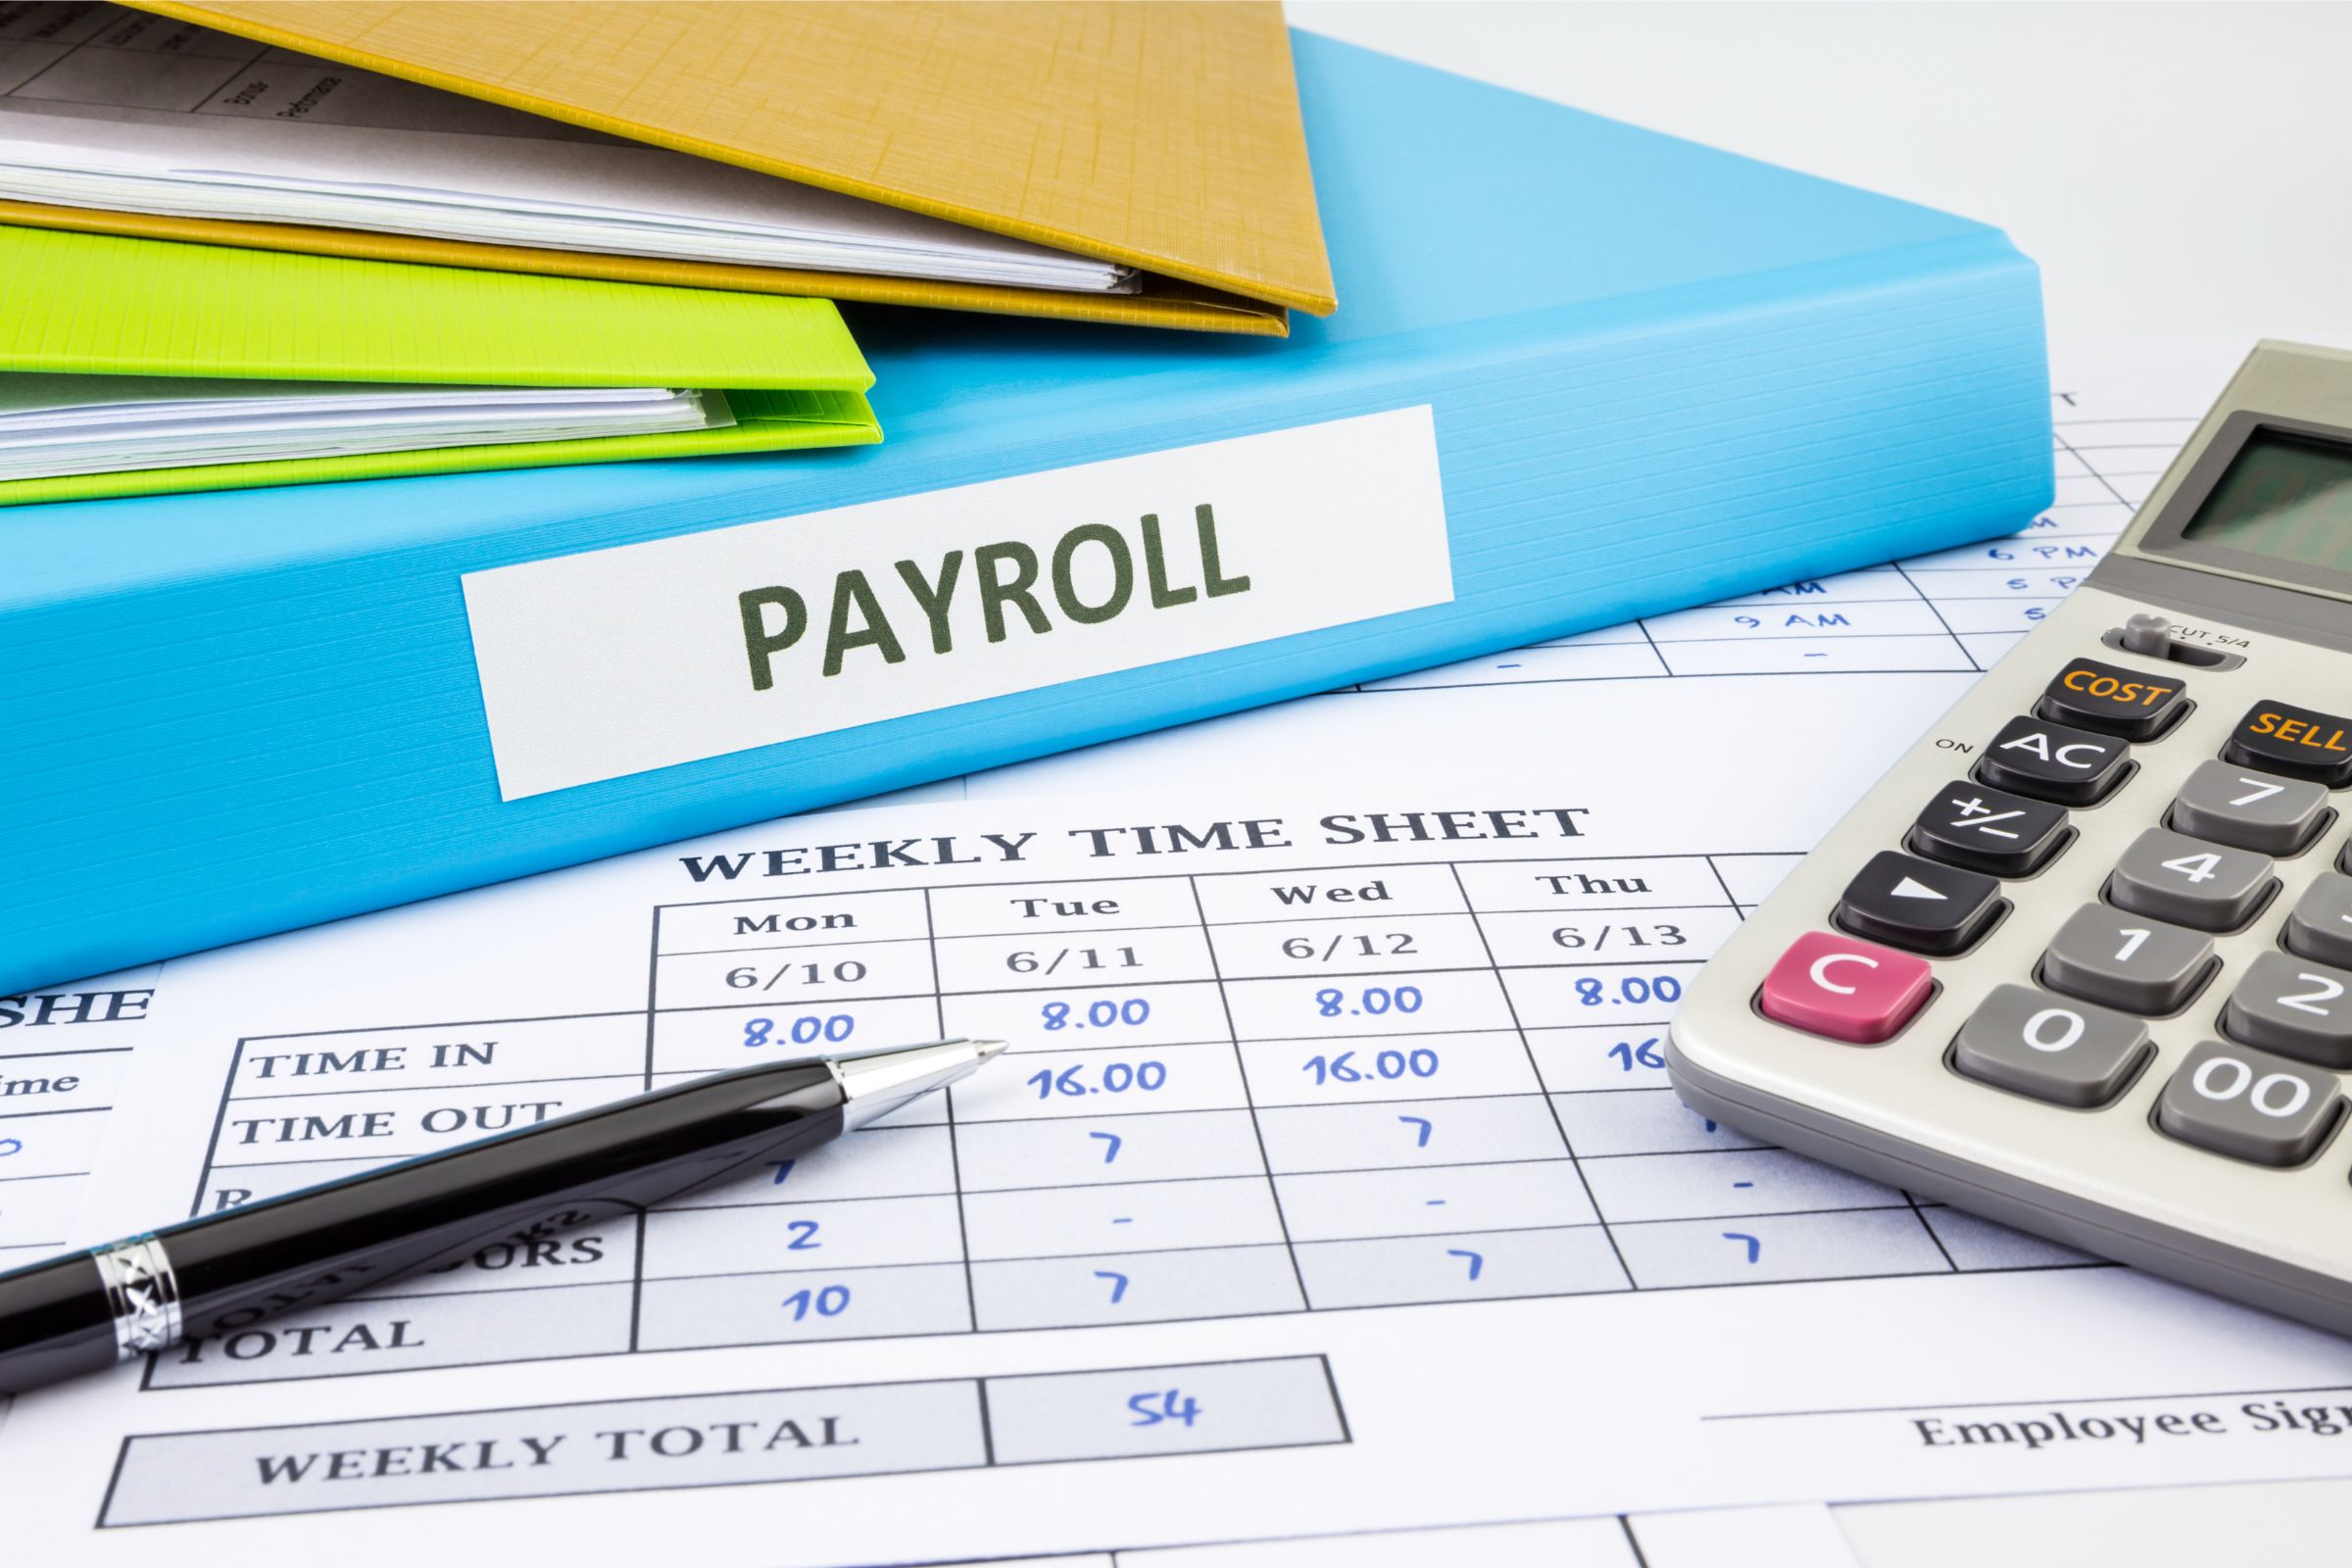
Bookkeeping also ensures compliance with tax regulations and deadlines. Businesses are required to file various tax forms, such as income tax returns, sales tax reports, and payroll tax filings.
Missing deadlines or failing to comply with tax regulations can result in penalties and interest charges. By maintaining accurate records and regularly reviewing tax obligations, business owners can ensure timely and accurate filings, avoiding costly penalties and maintaining good standing with tax authorities.
Hiring a Bookkeeper vs. Doing It Yourself
Deciding whether to hire a bookkeeper or handle bookkeeping tasks yourself is an important decision for small business owners. There are benefits and drawbacks to both approaches, and the best choice depends on the specific needs and resources of the business. Hiring a bookkeeper can provide professional expertise and free up valuable time for business owners to focus on core operations. Bookkeepers are skilled in maintaining accurate records, preparing financial reports, and ensuring compliance with tax regulations.
On the other hand, doing bookkeeping yourself can save money and provide a deeper understanding of the business’s financial health. Many bookkeeping software solutions are designed to be user-friendly, allowing business owners to manage their finances efficiently. By handling bookkeeping tasks personally, entrepreneurs stay closely connected to their financial data, enabling them to make informed decisions and identify potential issues early on. However, it requires a significant time investment and a willingness to learn and stay updated on bookkeeping practices.
For businesses with complex financial needs or limited time, hiring a bookkeeper may be the best option. A professional bookkeeper can provide valuable insights, ensure accuracy, and help the business navigate financial challenges. For smaller businesses with straightforward transactions and a desire to maintain control over their finances, doing bookkeeping in-house with the aid of software may be a practical and cost-effective solution. Ultimately, the decision should align with the business’s goals, resources, and capacity for managing financial tasks.
Conclusion: Taking Control of Your Business Finances
Mastering bookkeeping is a fundamental aspect of running a successful small business. By understanding the importance of bookkeeping, avoiding common mistakes, utilizing essential tools, and setting up an efficient system, business owners can take control of their finances and pave the way for growth. Organizing financial documents, preparing for taxes, managing cash flow, and deciding between hiring a bookkeeper or doing it yourself are all critical components of effective financial management.
Regular financial reviews ensure that business owners stay informed about their financial health, enabling them to make proactive and strategic decisions. Ultimately, mastering bookkeeping empowers entrepreneurs to achieve financial stability, make informed decisions, and drive their businesses toward long-term success. By implementing these ten essential tips, small business owners can elevate their bookkeeping game and unlock the full potential of their financial management practices.